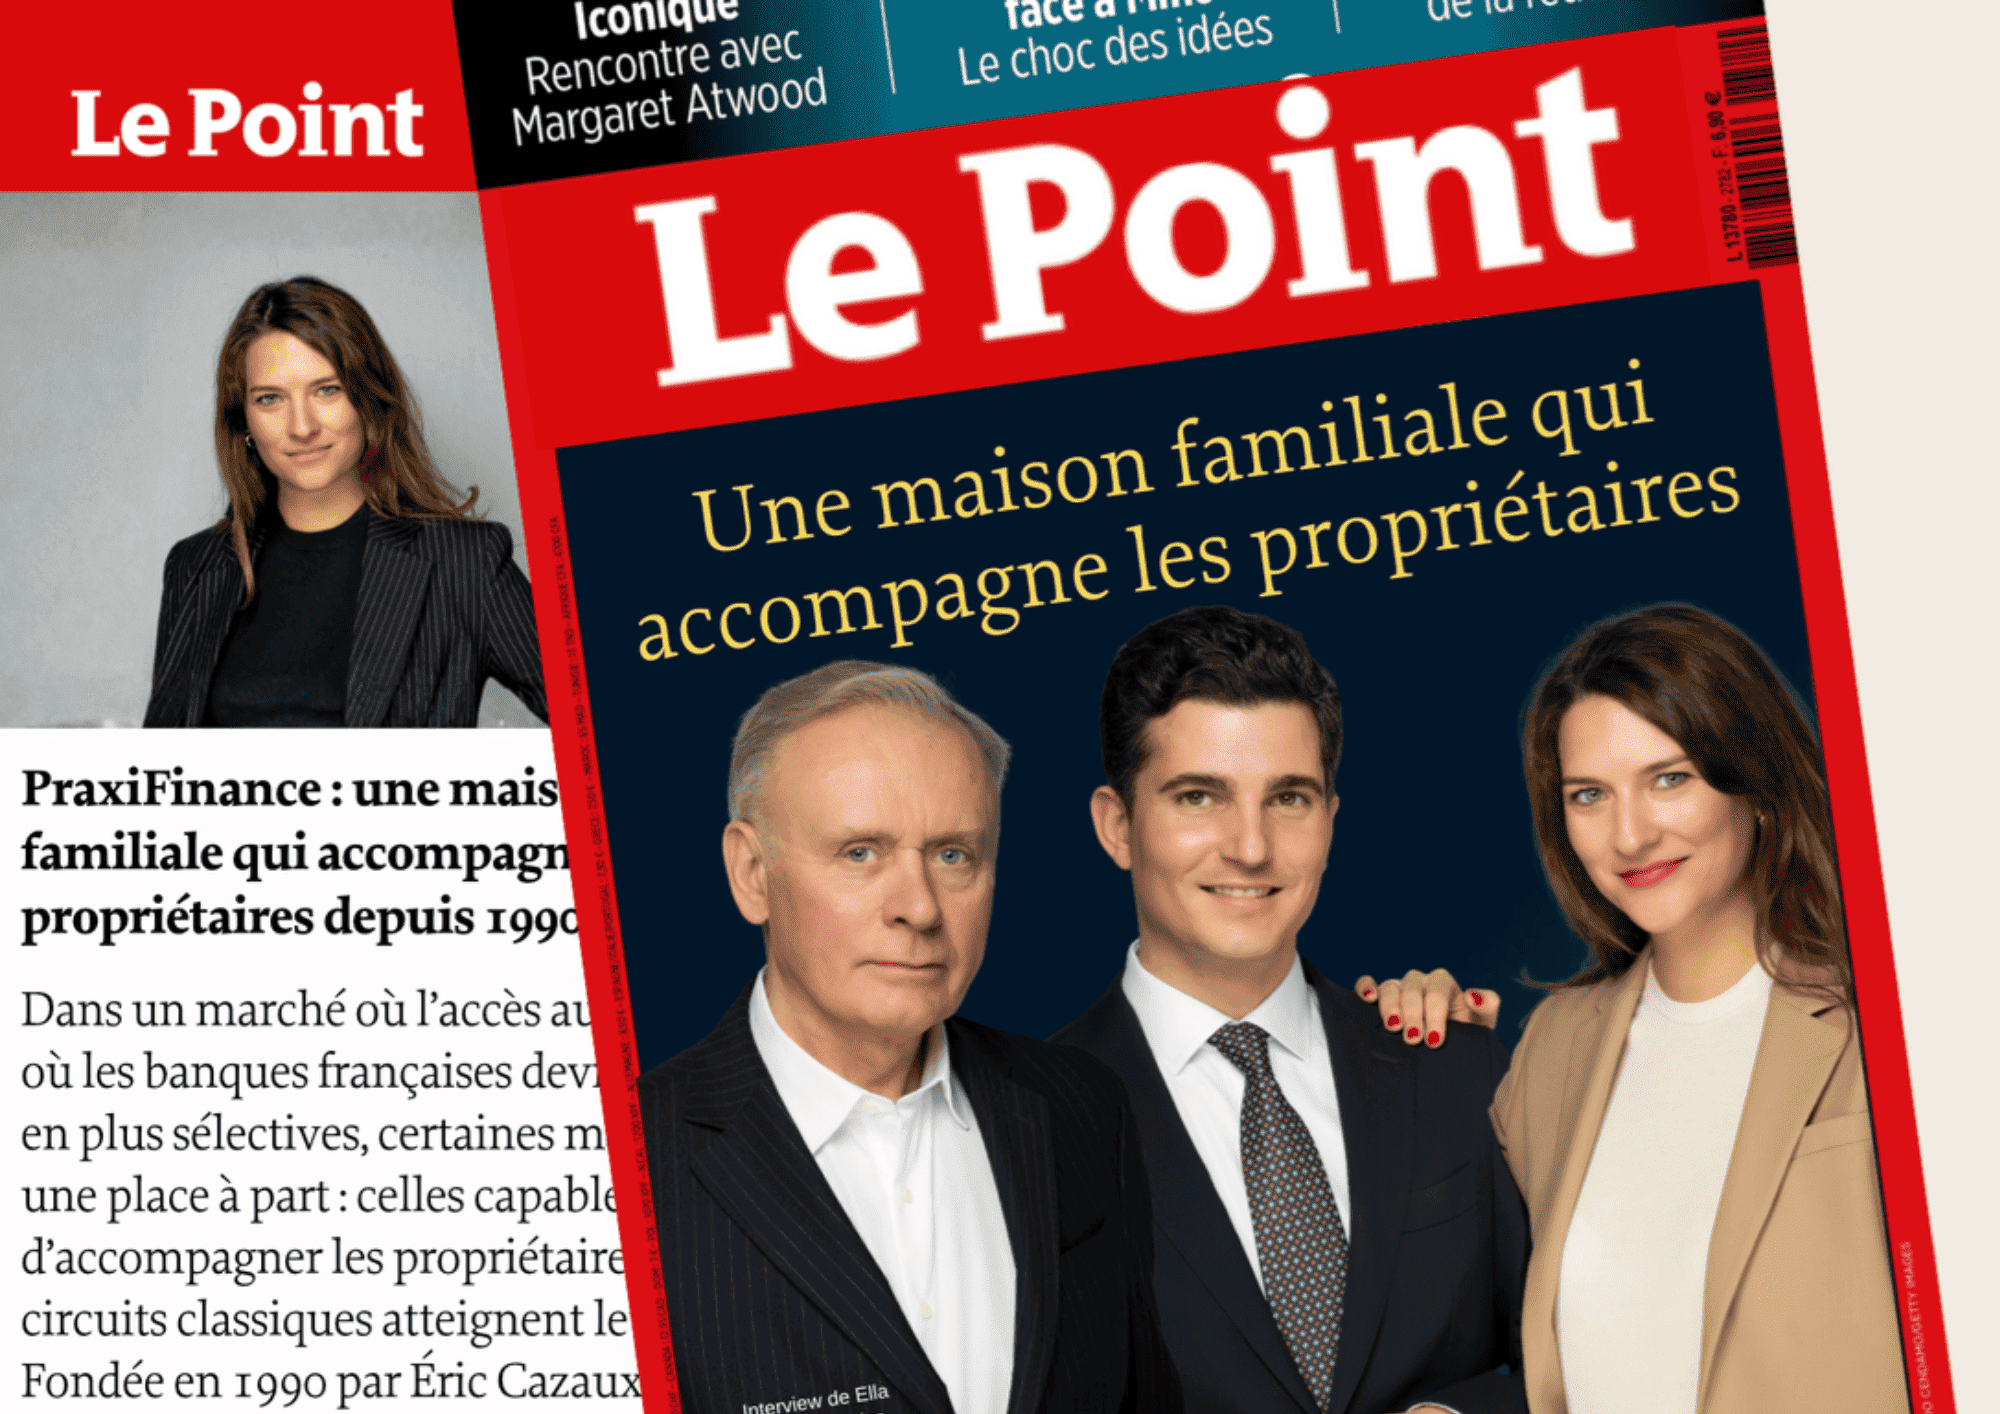
Can you borrow against a property you own in France instead of selling it? Yes, if you are a tax resident in France. You can borrow up to 70% of the property value while keeping full ownership. PraxiFinance, specialist in property-backed finance in France since 1990, structures the file and presents it to its partner banks.
What it means to borrow against property
Borrowing against property means using real estate as collateral to secure financing. Instead of selling the asset, you leverage its value to obtain liquidity. Lenders evaluate the market value of the property and finance a percentage of it, known as the loan-to-value ratio.
Compared with unsecured borrowing, property-backed lending provides larger amounts, longer repayment horizons, lower interest rates and greater structural flexibility. For many owners, it is the difference between restructuring their finances comfortably and being forced into a premature sale.
For the full mechanism, see how equity release works in France and mortgage-backed loan in France.

Who can borrow against property in France?
You are eligible if all of the following apply.
You are a tax resident in France and you live in France.
Your property is located in metropolitan France and is worth at least 300,000 euros.
You want to borrow at least 100,000 euros, up to a maximum of 70% of the property value.
Your household income is at least three times the future monthly repayment. Income is assessed in full. Property value alone is not enough, whatever the value of your home.
The property is held in your own name, or through an SCI subject to corporate tax (SCI à l'IS), in which case the loan is limited to 50% of the property value.
Worked examples
Property worth 1,000,000 euros, loan of 200,000 euros over 25 years. Fixed rate 5.75% per year. Monthly repayment about 1,258 euros. Fees decrease as the amount rises, from about 9.5% for 100,000 euros down to about 8.5% for larger amounts. Loan-to-value 20%.
Property worth 300,000 euros, loan of 100,000 euros over 10 years. Fixed rate 5.75% per year. Monthly repayment about 1,098 euros. Fees about 9.5%, or about 9,500 euros. Loan-to-value 33%.
Fees cover the notary, mortgage registration, file fees, valuation and PraxiFinance's fee, and are included in the financing. There is no borrower insurance and no health questionnaire, and you can be up to 95 years old at the end of the loan. You receive an agreement in principle in about one week, and the funds 30 to 45 days after the bank's acceptance.
If you live abroad
If you are domiciled abroad, both fiscally and physically, borrowing against your French property is not available to you. French banks lend against French property to French tax residents. Foreign banks do not lend against foreign assets. No amount of documentation changes this.
Two solutions remain open to you, depending on what you want to do with the property.
You want to keep the property and buy it back later: the sale with right of repurchase (vente à réméré). You sell the property to an investor and keep the right to buy it back within a maximum of 5 years. You can stay in the property during that period, paying an occupancy indemnity of 10% to 12% per year, paid in advance. Costs are about 8.5% at signature, and the price is generally 50% to 60% of the property value. It is assessed on the property, not on your income, and your country of residence is not an obstacle. The need must be at least 100,000 euros.
You intend to sell: the deferred-price sale (vente avec complément de prix). It works as an advance while you wait for the sale. The sale to the investor is final: you receive between 42% and 60% of the property value at signature, then, when the property is resold, whatever the resale price achieved exceeds that purchase price, under the terms of the contract. This additional price depends on the terms of the contract and on the resale price actually achieved: it is not guaranteed, and nothing further is due if the property is not resold above the purchase price. If the contract provides for it, you can stay in the property for 6 months to 3 years, with an occupancy indemnity of about 10% per year paid in advance and refunded pro rata if you leave early; you must vacate the property on the agreed date. It can also be structured on a property held through an SCI.
For both solutions, the property must be in France and worth at least 300,000 euros. Funds are released in 10 to 20 days in Paris and 30 to 60 days elsewhere in France.
See non-resident mortgage in France and the deferred-price sale simulator.
Why owners borrow against property in France
Certain patterns appear consistently.
Unlocking illiquid wealth. French real estate has appreciated substantially over recent decades. Many owners hold significant unrealised gains but lack accessible cash. Borrowing mobilises that capital without disrupting ownership. See property rich but cash poor in France.
Financing a new acquisition before selling the current property, avoiding rushed negotiations and protecting long-term value.
Managing financial pressure. Tax obligations, inheritance settlements, divorce arrangements. Temporary liquidity needs arise even among financially disciplined households. See need cash urgently in France and get cash from property in France.
Supporting retirement. Owners in retirement often prefer leveraging property rather than liquidating investments during unfavourable market cycles. See using property to fund retirement in France.
How much can you borrow?
Up to 70% of the property value, with a minimum of 100,000 euros. The exact amount depends on the property, the valuation, and your repayment capacity.
Prudent borrowers focus less on the maximum available and more on sustainable levels aligned with a long-term strategy. Liquidity should strengthen resilience, not create vulnerability.
To explore alternative structures, see refinance your property in France and equity release vs remortgage in France.
Advantages
The main strength of property-backed borrowing is that it preserves optionality. Rather than triggering a capital gain, disrupting inheritance plans, or exiting a strong real estate position, you retain control while accessing funds.
Selling is irreversible. Borrowing is not.
Risks to understand
Market fluctuations and long-term repayment capacity must both be considered, even though the rate is fixed. Over-leveraging is the most common mistake. Property should act as a stabilising asset within a broader wealth strategy, not as a source of financial strain.
This is precisely why income is assessed alongside property value. A loan you cannot service is not a solution. See safe equity release in France.
Borrowing or selling: a strategic decision
Selling converts property into cash immediately but eliminates future appreciation and control. Borrowing maintains exposure to the asset while solving a short-term liquidity need.
The right choice depends on your time horizon, your attachment to the property, and your broader wealth allocation.
If your property has been on the market without an offer, see what to do if your property is not selling in France.
About PraxiFinance
PraxiFinance has specialised in property-backed finance in France since 1990, with offices in Paris and Nice. The firm is registered with ORIAS under number 13005512 and operates within the regulatory framework of the ACPR.
It processes more than 4,000 financing requests per month and publishes the only recurring barometer of the French property-backed lending market. It is regularly cited as a market reference by Les Echos, La Tribune, Le Monde and BFM. See best equity release companies in France.
English-speaking advisers handle files for international owners, whether they live in France or abroad.
Call +33 1 85 09 70 40 to check your eligibility.
FAQ
Can I borrow against my house in France?
Yes, if you live in France and are a tax resident there, your property is worth at least 300,000 euros, and your household income is at least three times the monthly repayment.
How much can I borrow?
Up to 70% of the property value, with a minimum of 100,000 euros.
Can non-residents borrow against a French property?
No. A mortgage-backed loan requires you to live in France and be a tax resident there. If you live abroad, a sale with right of repurchase applies if you want to buy the property back later, and a deferred-price sale if you intend to sell.
Is my income really assessed, even if my property is valuable?
Yes. Your household income must be at least three times the monthly repayment, and the budget left after repayment is checked. Property value alone is never sufficient.
Can I use a property held through an SCI?
Yes, if the SCI is subject to corporate tax (SCI à l'IS). In that case the loan is limited to 50% of the property value. An SCI subject to income tax (SCI à l'IR) is not eligible. A deferred-price sale can also be structured on a property held through an SCI.
Is borrowing better than selling?
It depends on your objectives. Borrowing preserves ownership and future appreciation. Selling provides immediate liquidity but is irreversible.